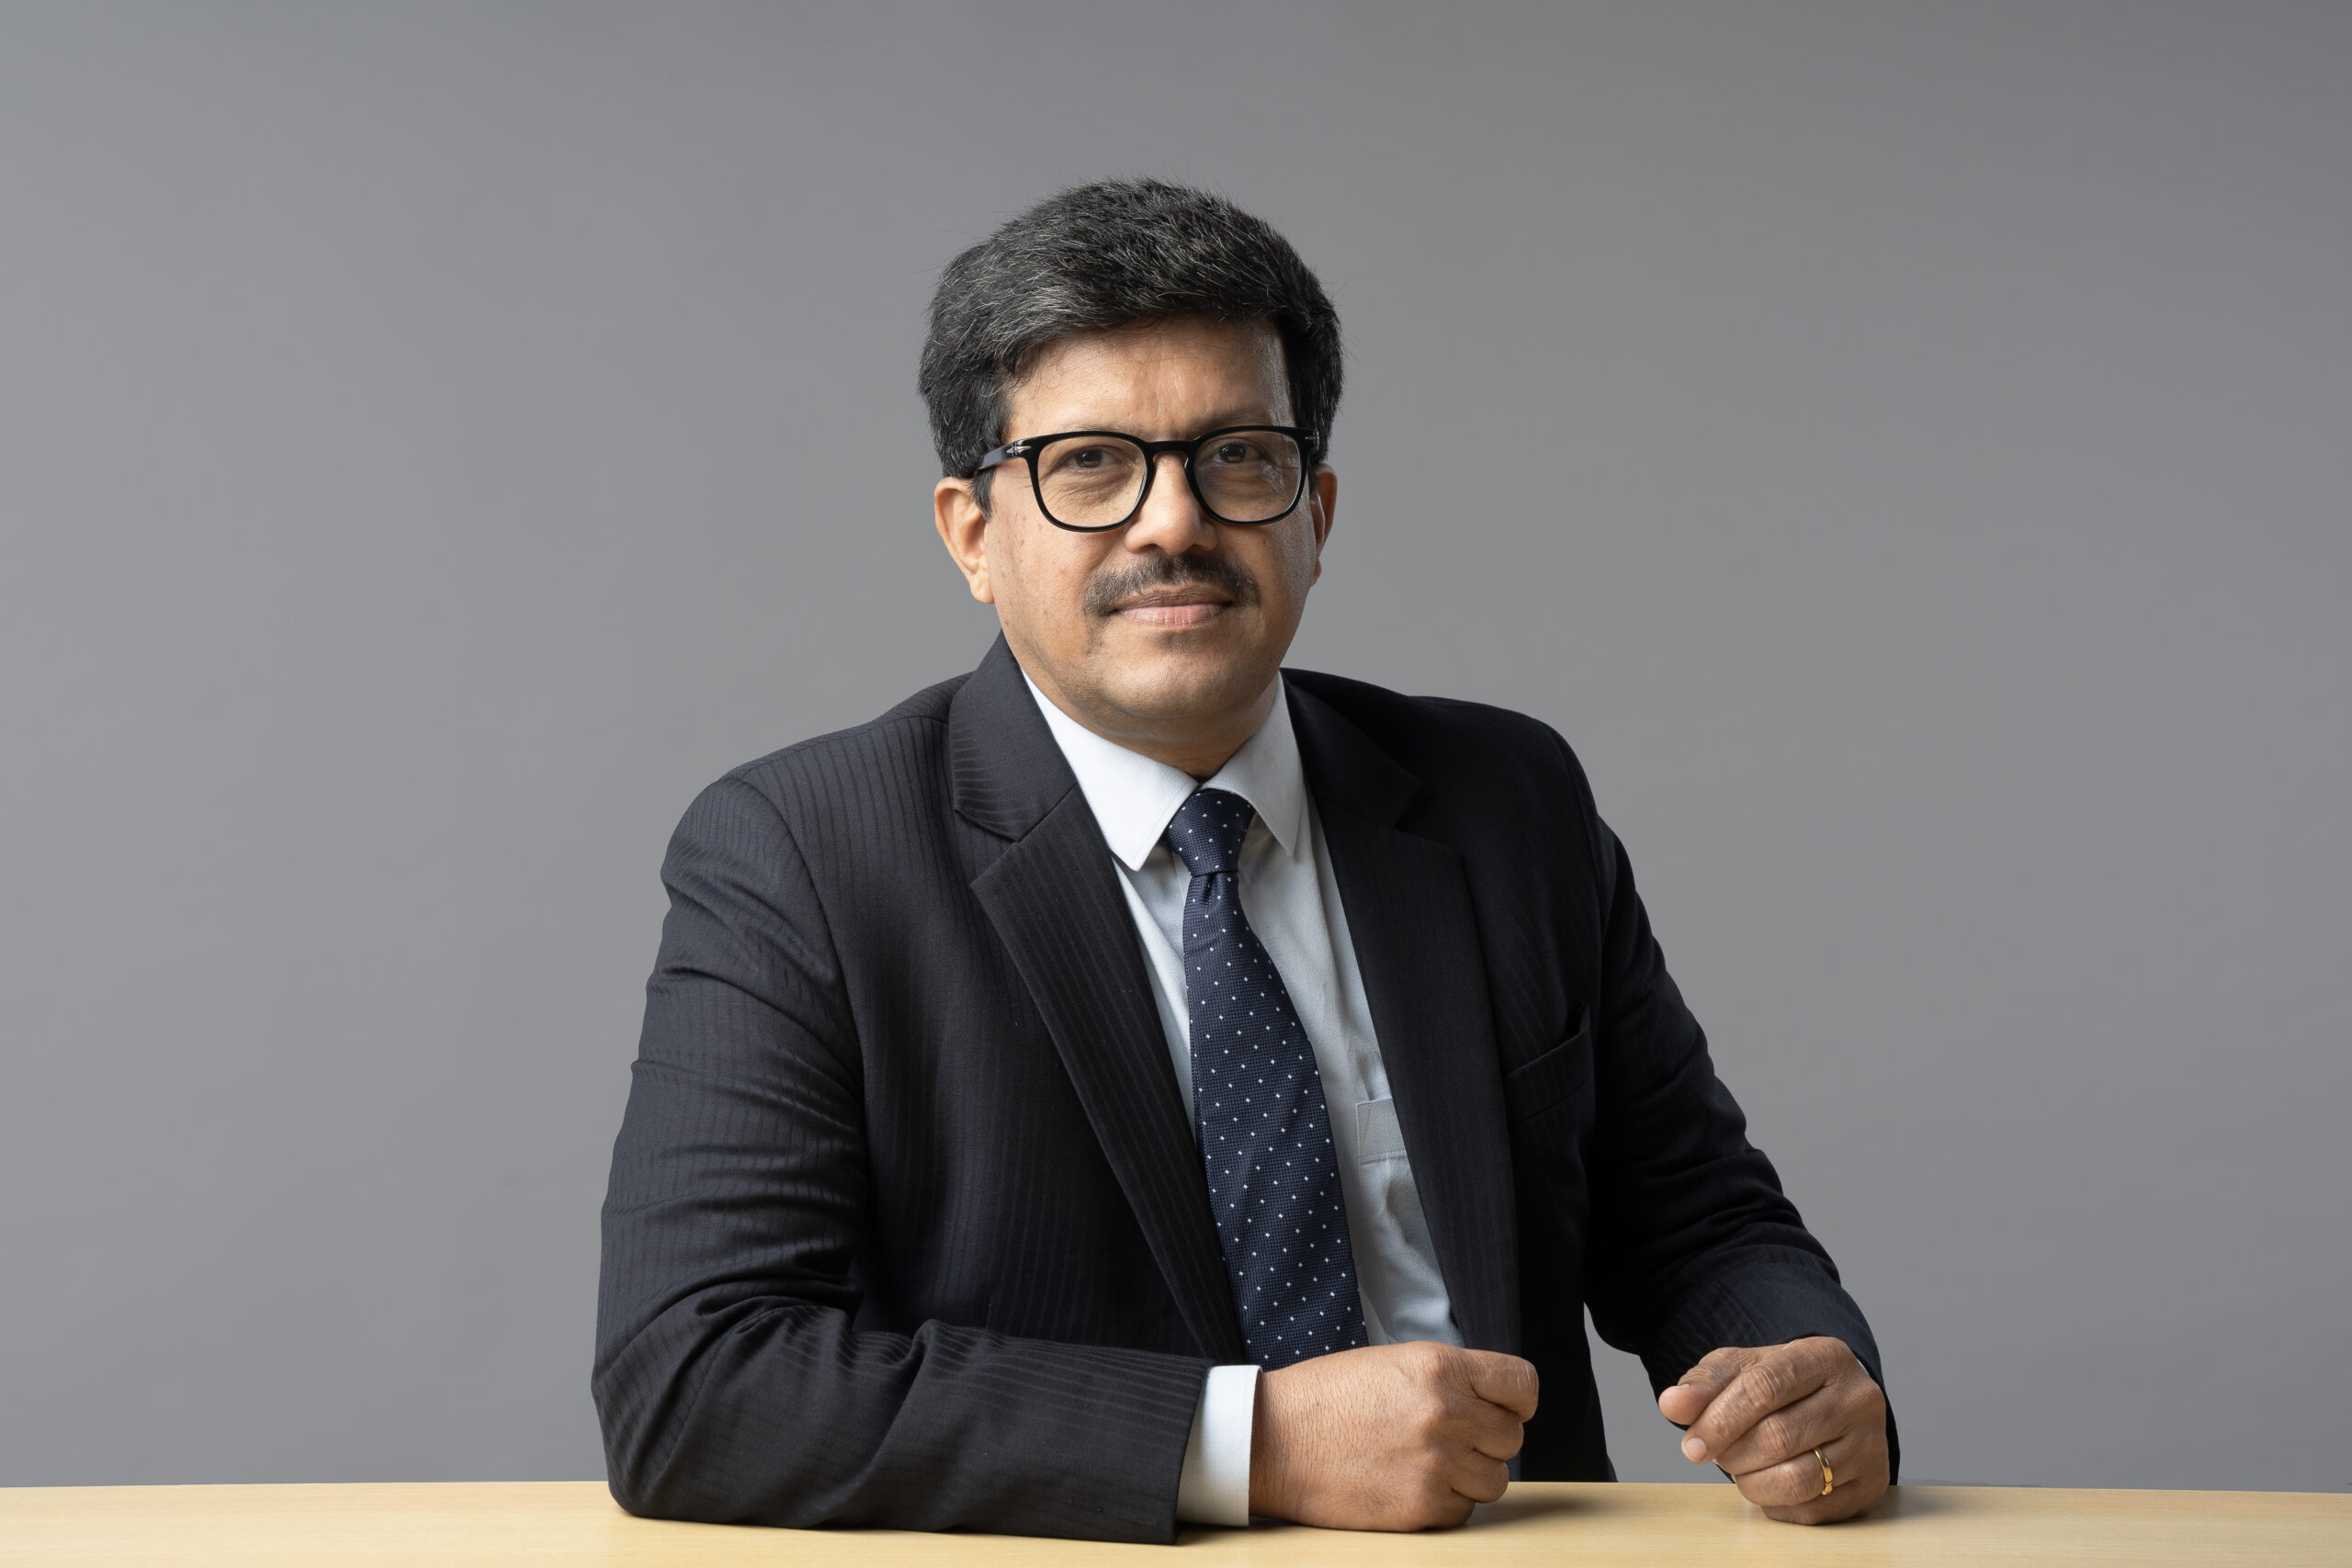
India’s tourism and hospitality sector is evolving rapidly, creating diverse financial needs across hotels, travel businesses, restaurants and allied services. In an interaction with Disha Shah Ghosh, Vijay Shetty, Group Head – Commercial Banking Group, Axis Bank, discusses the growing scope for tourism-focused banking, sector-specific financial challenges, and how banks can support businesses with credit, digital solutions and technology.
Q. What kind of scope do you see for tourism-focused banking products in the Indian market?
As India’s tourism industry contributes 5.22% of the national economy and supports 13.34% of total employment, the scope is considerable, and it continues to widen year on year. Tourism is an ecosystem that brings together hotels, resorts, homestays, restaurants, tour operators, transport providers, event companies, artisans and allied services. Each participant carries its own banking requirement, whether working capital to manage seasonal demand, term finance for expansion, collections and payment infrastructure, foreign exchange, or employee banking. A tourism-focused proposition allows a bank to serve this entire chain through solutions shaped to the way these businesses actually operate.
The scope, lies in products curated to the very nature of this trade. Underwriting that accommodates seasonality and occupancy cycles, appraisal that draws upon hospitality metrics such as occupancy rates, average room rates and revenue per available room, and due regard to customer reviews and ratings on the common travel and booking platforms, all of which offer a dependable read of an establishment’s standing. Lending propositions can then be tailored to these realities, with repayment obligations aligned to the rhythm of cash flows through lean and peak months.
At Axis Bank, Tourism and Hospitality is one of our priority sectors, and we have curated propositions for it, among them a dedicated hotel lending proposition and a current account bundle designed for tourism and hospitality enterprises.
Q. What are the key banking and financial challenges faced by businesses across the tourism and hospitality ecosystem, and how is Axis Bank addressing these needs?
The banking and financial requirements of the tourism and hospitality sector are distinct, given its cyclical revenues, diverse business models and evolving customer expectations.
Key Banking & Financial Challenges
• Access to timely and adequate credit, particularly for businesses with seasonal income patterns.
• Managing liquidity and maintaining healthy cash flows across peak and lean periods.
• Handling collections, payments, transaction banking and foreign exchange requirements efficiently.
How Axis Bank is Addressing These Needs
• Providing working capital facilities, term loans, project finance and supply chain finance solutions.
• Offering cash management, POS solutions, payment gateways, commercial cards, trade and forex services.
• Delivering dedicated current account and lending propositions designed for the Tourism & Hospitality sector.
At Axis Bank, we complement these offerings with a sector-focused approach, working closely with businesses to understand their operating models, customise solutions to their requirements, and remain aligned with industry needs through continued engagement with bodies such as Federation of Hotel and Restaurant Association of India Travel and tourism Association of Goa, PHDCCI (Tourism and hospitality wing) etc.
Q. What emerging trends do you see shaping the tourism and hospitality sector in India, and how is Axis Bank preparing to support businesses and stakeholders as the sector evolves?
India’s tourism and hospitality sector is witnessing a shift in travel behaviour, with demand becoming more diverse, experience-led and digitally enabled.
Key Emerging Trends:
• Growth in domestic tourism, driven by better connectivity, rising disposable incomes and greater travel aspirations.
• Increasing preference for experiential travel, weekend getaways and staycations, with travellers seeking personalised and immersive experiences.
• Rising demand across niche segments such as wellness, heritage, spiritual, wedding and MICE tourism.
How Axis Bank is Preparing for the Future
• Expanding engagement across the ecosystem, including hospitality businesses, travel aggregators, tourism operators and state tourism bodies.
• Enabling businesses with customised banking solutions, access to capital, digital payment infrastructure and transaction banking capabilities.
• Developing sector-focused propositions for emerging travel segments and increasing outreach across Tier 2 and Tier 3 markets.
At Axis Bank, our focus is to remain closely aligned with the sector’s evolution by combining industry understanding with tailored financial solutions. Through deeper engagement with tourism stakeholders and industry associations, we seek to support businesses as they adapt to changing traveller preferences and capitalise on new opportunities emerging across the ecosystem.
Q. How can banks play a larger role in supporting the growth of small and mid-sized businesses in the tourism and hospitality sector, particularly as they look to expand, adopt technology and improve their operations?
Small and mid-sized enterprises form the greater part of India’s tourism and hospitality ecosystem, and their ability to scale often turns on timely finance, sound technology and efficient business practices. Banks are well placed to serve a far broader purpose than the provision of credit alone. They can act as facilitators of enterprise, offering advisory guidance, digital tools, payment infrastructure, cash-flow management and access to wider commercial networks.
At Axis Bank, we have a suite of solutions for MSMEs aimed at financing expansion plans, enabling digitisation, simplifying collections and payments, extending employee banking, and helping enterprises connect across the value chain through extensive 6,200+ branch network with reach Tier 1/2/3 regions. These are supported by:
• Credit assessment that accommodates seasonal earnings and hospitality performance metrics.
• Digital collections and payment acceptance, from point-of-sale terminals to payment gateways.
• Trade, foreign exchange and commercial card solutions for enterprises serving inbound travellers.
• A network of over 6,200 branches, offering wide reach across Tier 2 and Tier 3 markets.
As these businesses modernise their operations and enhance the experiences they offer, a banking partner can contribute by pairing technology-enabled solutions with attentive relationship support. In doing so, we help enterprises build resilience, improve efficiency and pursue new opportunities with assurance, which in turn supports the wider progress of the sector and the communities it sustains.
In the period ahead, our intent is to take this further through simpler digital onboarding, credit assessment informed by transaction and platform data, and closer work with aggregators and industry bodies, so that smaller enterprises in every part of the country find formal banking easier to access.